 RUNNERS / ROBINHOOD
OFY, the card that wants to leave savings alone
OffYield arrives on Robinhood Chain with an easily understood idea: spend the interest without spending the deposit. Between a USDG vault, prepaid cards and questions about the token’s role, its launch opens a discussion about what a crypto “neobank” actually delivers. Reported ATH: $2.41 million on September 29 at 21:05 Paris time.
At 21:00, a question behind the card
What does holding your token actually do for its holder? That is the question Sllab asks in the replies to OffYield’s launch at 21:00 on September 29. The website describes a working deposit, interest becoming spendable and a card. But where does OFY fit into that arrangement? The question runs through the project’s first evening. [5]
Five minutes later, according to the observation supplied to the editorial team, its market capitalization reaches $2.41 million. The proximity of those timestamps establishes no causality. It locates a discussion already accompanying the rise: an application can attract interest through its use case while leaving open the value it brings to token holders.
A launch borrowing fintech’s visual language
At 20:08, @offyield announces OFY with the exact contract examined here. DEX Screener dates the main OFY/ETH pair to 20:08 as well. The website displays the same address. These matches connect the market under review to the project’s communications, beyond a name or ticker that could be reused elsewhere. [1] [2] [4]
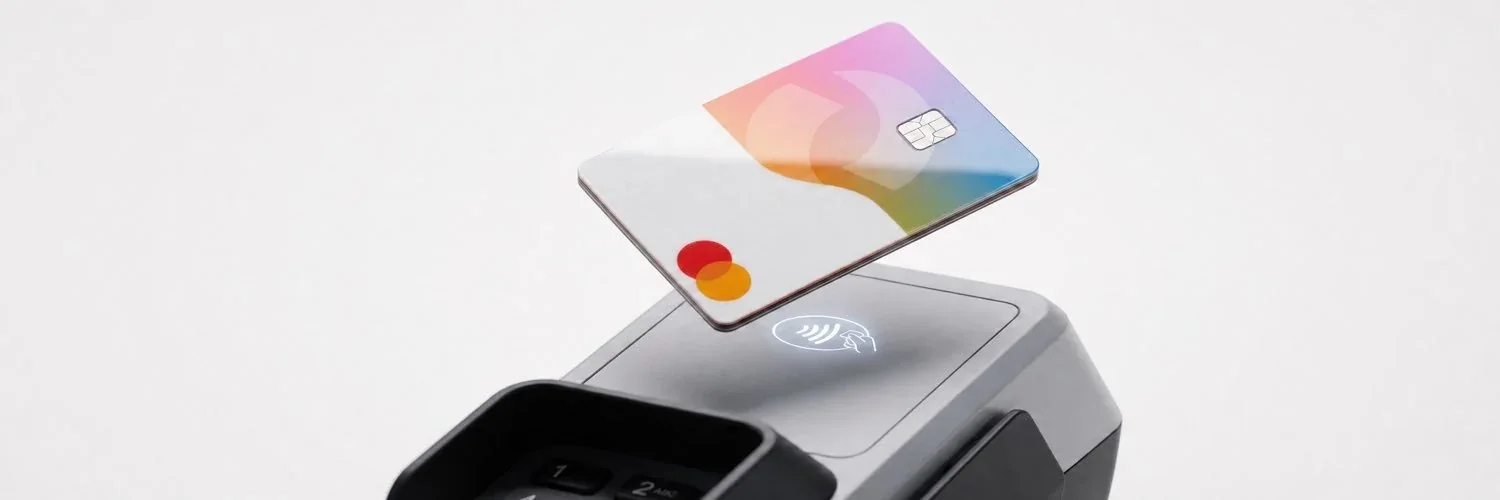
The promotional artwork shows a pastel card suspended above a payment terminal. Little text, ample white space, a chip and the familiar contactless gesture: we read these as the visual conventions of a financial application intended for everyday life. OffYield turns that promise into a name: living off what savings generate instead of drawing them down.
At 21:08, Poti compares the project with Avici and asks whether it signals a Robinhood neobank trend. This is a participant’s comparison, not an established relationship. The word chiefly places OFY in a readily understood category. OffYield nevertheless states that it is independent of Robinhood, Morpho and Paxos. Building on a chain does not make the application their banking service. [2] [6]
Two balances, one rule and a lending market
The documentation describes an application that does not hold users’ keys, in early access with deposit caps. A user supplies USDG; the vault is intended to route it into the Steakhouse USDG vault on Morpho. Interest comes from lending, at a variable rate. Principal and available yield are accounted for separately: an excessive charge should be rejected rather than topped up from the deposit. [3]
That separation is the core of the proposed product. It gives a savings discipline a concrete form: the spending balance should not consume the reserve. It does not mean the reserve is protected from every loss. The documentation explicitly anticipates that losses in the underlying market may reduce recoverable value, and says deposits have no government-backed bank insurance. [3]
Another essential distinction is that deposits and interest never pass through OFY, according to the website. Buying the token therefore does not amount to depositing USDG in the vault. The two actions carry different expectations even though the brand brings them together. This supplies an initial answer to Sllab: the token’s utility must be sought somewhere other than the production of lending interest. [2] [3]
Some cards available, others still promised
The documentation presents prepaid cards supplied by CryptoRefills and a reloadable card still in development. It sets out constraints that a banner cannot communicate: online use, product-dependent fees and the absence of 3-D Secure, which can cause some merchants to decline payments. Its example uses about $33.60 of interest to purchase a $30 prepaid Visa, including fees. [3]
At 21:29, the team announces physical cards for the fourth quarter and reloadable cards around the following week. It also says its non-reloadable cards work with Apple Pay and Google Pay. These are the team’s availability claims and timetable; we did not purchase a card or execute a payment to test them. BOLD specifically says in the launch thread that the cards are what attracts his attention. [7] [13]
The same announcement says card purchases are now open even to people who have not generated yield. This broadens the original pitch. The vault offers spending from interest; the shop also wants customers who prefer not to wait. The project thus combines a savings tool with more immediate card access, two uses that need to be separated when reading its reported figures. [7]
Cashback enters the token debate
At 21:40, OffYield claims roughly $9,000 in cards and $250 in cashback paid during its first hour. The account says accessing 5% cashback requires connecting the wallet holding OFY to the dashboard and purchasing a card there. These are team-reported figures, not independently verified sales or evidence of a sustainable token return. [8]
The documentation still discusses this cashback in the future tense, while the post says it has started. That update gap is useful to identify: the pages should not all be treated as describing exactly the same product stage. The documentation also says cashback is funded separately from deposits and their interest. [3] [8]
Reactions extend beyond enthusiasm. In the launch replies, @vvalter argues that establishing a company and connecting a card provider are insufficient to make the offering distinctive. This challenges differentiation; it does not establish that the product fails to work. It nevertheless raises the commercial question behind the narrative: why retain this application rather than access similar services elsewhere? [14]
What the security review actually covers
At launch, OffYield describes itself as a Wyoming-registered LLC and invokes Shieldify to reassure readers about its code. The document available in Shieldify’s repository supplies a narrower scope: a review dated September 11 covering OffyieldVault.sol. It lists two medium, four low and six informational findings, all marked fixed in its summary table. [9] [10]
That report documents work on the vault. It does not by itself certify the entire card shop, every integration or the identity of the code actually deployed. The project’s company-registration claim does not establish banking status either. These materials make assertions more examinable without turning “audited” into a blanket guarantee. [9] [10]
After $2.41 million, delivering the timetable
The evening continues after the reported peak. At 22:08, the account announces work on an Android application; at 22:38, it publishes a preview described as showing the interface and code. These posts follow 21:05. They extend the story and cannot be presented as the triggers of that particular market milestone. [11] [12]
The ATH retained is the observation supplied to the editorial team: $2.41 million at 21:05 Paris time on September 29, 2026. OFY has found an immediately legible proposition: a card that leaves savings alone. Its next chapter will depend on more concrete questions about what ships, what using it costs and what the token contributes once the novelty of launch fades.
Sources
Sources consulted on 29 September 2026. Figures reflect the cited snapshots and are not updated live.
- OffYield — annonce du lancement et contrat, 29 septembre à 20 h 08 (Paris)
- OffYield — site officiel et présentation du produit
- OffYield — documentation du coffre, du rendement et des risques
- DEX Screener — OFY / ETH, paire Uniswap v4 sur Robinhood
- Sllab — question sur l’utilité du token, 21 h 00 (Paris)
- Poti — rapprochement avec Avici, 21 h 08 (Paris)
- OffYield — cartes physiques, rechargeables et ouverture des achats, 21 h 29 (Paris)
- OffYield — chiffres de cartes et cashback annoncés, 21 h 40 (Paris)
- Shieldify — revue de sécurité OffYield datée du 11 septembre 2026
- OffYield — présentation de la société et de l’audit dans le fil de lancement
- OffYield — annonce du développement Android, 22 h 08 (Paris)
- OffYield — aperçu de l’application mobile, 22 h 38 (Paris)
- BOLD — intérêt déclaré pour la sortie des cartes
- 匿鱼 (W) — critique du caractère différenciant du produit